Canada Insulin Delivery Devices Market Analysis Industry Trends and Forecast to 2034: Segmented by (By Product Type, By Distribution Channel, By Region) - Growth, Market Size, Future Prospects & Competitive Analysis, 2024-2034
Overview
Market Dashboard
Canada · 2024–2034 · placeholder estimates
Values shown here are placeholder estimates, not researched figures. Researched 2024 historical, 2025 base-year and 2026–2034 forecast values are prepared with the
full report.
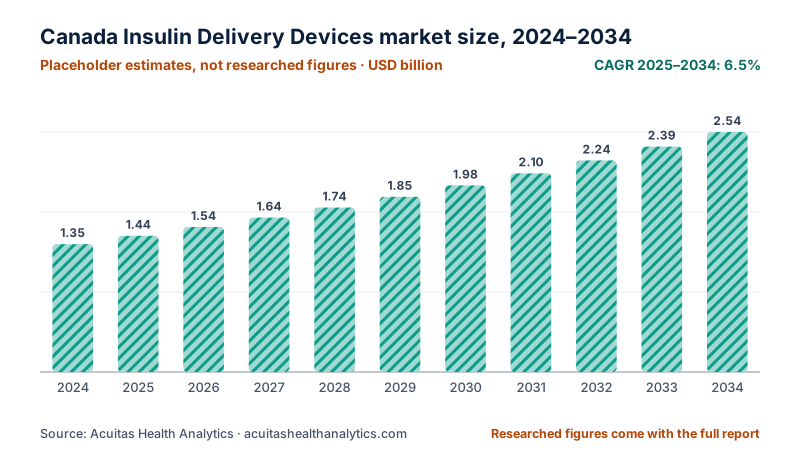
Estimate 2024$1.35 BnPlaceholder estimate
Estimate 2025$1.44 Bn8% of the global market
Projected 2034$2.54 Bn 76.3%Adds $1.10 Bn over 9 forecast years
CAGR 2025–20346.5%Faster than 22% of 173 Medical Devices markets here
Novo Nordisk A/S, Medtronic, Sanofi, Abbott Laboratories, Eli Lilly and Company and 1 more (see all)
Regulator in Canada
Health CanadaSource: Health Canada. Checked 14 Nov 2026.
Active clinical trials
27 in CanadaSource: ClinicalTrials.gov, Studies recruiting, active or not yet recruiting, in Canada. Retrieved 9 Nov 2026.
Formats
PDF, PPTX, XLSX
Sizes and growth here are placeholder estimates, not researched figures. Researched figures come with the full report.
The Canada Insulin Delivery Devices Market Executive Summary
Diabetes is a disease that requires careful administration of Insulin through Insulin delivery devices to maintain blood sugar levels. These are insulin pens (reusable and disposable), that can administer a continuous supply of insulin through a catheter known as insulin pump, syringe injections, and jet injectors which are needleless. Other creative possibilities are inhalers and patches. These devices assist patients to regulate blood glucose levels, convenience and advance diabetes self-management with facilities such as programmable dosage and tracking. The IDF Diabetes Atlas (2021) reports that 10.5% of the adult population (20-79 years) has diabetes, with almost half unaware that they are living with the condition.
The global market for insulin delivery devices is expanding at a fairly constant rate due to increasing rates of diabetes, innovative technologies, and high consumer demand for improved insulin administration essentials. Leading vendors include Medtronic, Novo Nordisk, and Eli Lilly, while regions such as North America and Asia-Pacific exhibit the highest level of technology maturity. Some of the challenges include high costs, stringent regulations, and competition from other diabetes oral tablets. Future trends in innovation include the use of artificial intelligence, wearable technology, and biosimilar medication that is cheaper and accessible to the population.
Canada Insulin Delivery Devices market size, 2024–2034. Placeholder estimates; researched figures come with the full report. Source: Acuitas Health Analytics.
Canada Insulin Delivery Devices Market Dynamics
Market Growth Drivers
The increasing incidence of diabetes, influenced by urban development, an aging demographic, and shifts in lifestyle, serves as a significant catalyst, with a growing population of elderly and overweight individuals necessitating insulin therapy. Technological innovations, including intelligent insulin delivery systems and continuous glucose monitoring tools, significantly improve diabetes management, while advantageous reimbursement frameworks and escalating healthcare investments in developing regions further bolster market expansion.
Opportunity
Innovations in artificial pancreas systems (APS) are poised to enhance precision and ease of use, thereby improving glycemic control. Cutting-edge delivery modalities such as transdermal patches and inhalable insulin are anticipated to offer non-invasive and less frequent administration alternatives. The incorporation of digital health technologies, encompassing mobile applications and data analytics, will facilitate a more customized and proactive approach to diabetes management. Furthermore, the expansion of healthcare infrastructure and increased awareness in emerging markets, particularly in Asia and Africa, create opportunities for affordable insulin solutions.
Market Restraints
The elevated expenses associated with advanced medical devices, such as insulin pumps and smart pens, hinder their adoption, particularly in developing nations with constrained healthcare budgets. Product recalls and safety apprehensions, including cybersecurity vulnerabilities related to connected devices, can undermine consumer confidence and impede market growth. Practical challenges, such as the size and discomfort of certain devices, further restrict patient acceptance. Moreover, rigorous regulatory standards may postpone the launch of innovative products, thereby decelerating market expansion.
Competitive Landscape for Insulin Delivery Devices Market in Canada
August 2024, FDA Clears First Device to Enable Automated Insulin Dosing for Individuals with Type 2 Diabetes. Agency Supports Broader Access to Innovative Technology in Diabetes Management.
February 2024, Tandem Diabetes Care, Inc., a leading insulin delivery and diabetes technology company, announced the United States commercial launch of its new Tandem Mobi, the world’s smallest, durable automated insulin delivery system for people living with diabetes.
June 2024, Insulet Corporation has announced that its Omnipod 5, a tubeless automated insulin delivery system compatible with Dexcom G6 and Abbott FreeStyle Libre 2 Plus continuous glucose monitors, is fully available in the U.K. and the Netherlands. This marks the first AID system integrated with both leading CGM brands and is approved for use by individuals aged two years and older with type 1 diabetes.
June 2024, CeQur Simplicity™, a Wearable Mealtime Insulin Delivery Device, Obtains FDA-Clearance for 4 Days of Wear to Further Simplify Diabetes Management.
May 2025, FDA Cleared New Insulin Pump and Algorithm-Based Software to Support Enhanced Automatic Insulin Delivery. Agency Continues to Support Innovation of Next-Generation Technology in Diabetes Management.
Mergers and Acquisitions
February 2024, Catalent was recently acquired by Novo Holdings for $16.5 billion. This deal was slated to close later in 2024. As part of the deal, Novo Nordisk has agreed to acquire three fill-finish sites from Novo Holdings for $11 billion—the sites are in Italy, Belgium, and Bloomington, IN, in the U.S.
May 2025, Medtronic plc announced its acquisition of EOFlow Co. Ltd., the manufacturer of the EOPatch®, a tubeless, wearable, and fully disposable insulin delivery device. This acquisition, combined with Medtronic's Meal Detection Technology™ algorithm and next-generation continuous glucose monitor (CGM), is expected to enhance Medtronic's ability to meet the diverse needs of individuals with diabetes, regardless of their treatment preferences or stage in their diabetes management journey.
Healthcare Policies and Regulatory Landscape for Insulin Delivery Devices Market in Canada
Insulin Delivery Devices in Canada: rules, payment and research
Health Canada licenses Class II, III and IV medical devices; Class I devices are sold by companies that hold an establishment licence.[1] Each province and territory runs public health insurance under the Canada Health Act, which covers medically necessary hospital and doctor services.[2] ClinicalTrials.gov lists 27 studies on Insulin Delivery Devices that are recruiting, active or about to start in Canada.[3] Diabetes (adults): 6.8% of adults in 2022, the latest WHO figure for Canada.[4]
Numerous nations, especially in North America, possess comprehensive reimbursement policies that facilitate patient access to advanced diabetes management solutions. Nonetheless, coverage may vary, with developed markets typically providing extensive support while developing regions encounter challenges. Emerging markets such as India and China are anticipated to experience advancements in reimbursement as their healthcare systems evolve. Furthermore, policy modifications are influencing the market, with an increasing emphasis on preventive care, enhanced support for telehealth, and expedited regulatory approval processes improving access to and adoption of novel technologies.
8.2 Government Initiatives / Intervention programs
The insulin delivery devices market is segmented based on various criteria, allowing for a comprehensive understanding of its dynamics and growth potential. Here are the primary segments identified:
Other companies that free public records show in this market: trials they lead, US approvals and WHO prequalification. They are not part of our key players research. Each count opens its source.
Also active in this area, from free public records
Source: ClinicalTrials.gov, Active studies (recruiting, about to start or running) each company leads, found with this market's trial search, worldwide. Retrieved 13 Nov 2026.
Source: FDA 510(k) and PMA databases, 510(k) clearances and PMA approvals since 2015 for devices whose name has this market's words. Retrieved 13 Nov 2026.
Beyond the market numbers
Research, trials and patients
What doctors and scientists are doing in Insulin Delivery Devices right now, from free public sources.
How big is the Insulin Delivery Devices market in Canada?
Placeholder estimate: about $1.44 Bn in 2025, rising to about $2.54 Bn by 2034. These are early estimates, not researched figures; the researched values come with the full report.
How fast is the Insulin Delivery Devices market in Canada growing?
Placeholder estimate: about 6.5% a year (CAGR, 2025–2034). The researched growth rate comes with the full report.
What segments does the Insulin Delivery Devices market report cover?
The report splits the market by product type (Insulin Pens, Insulin Syringes, Insulin Pumps, Jet Injectors and more) and distribution channel (Hospital Pharmacies, Retail Pharmacies, Online Sales, Diabetes Clinics/Centers).
Who are the key players in the Insulin Delivery Devices market?
Key players include Novo Nordisk A/S, Medtronic, Sanofi, Abbott Laboratories, Eli Lilly and Company and Wockhardt Ltd..
What is driving the Insulin Delivery Devices market?
The increasing incidence of diabetes, influenced by urban development, an aging demographic, and shifts in lifestyle, serves as a significant catalyst, with a growing population of elderly and overweight individuals necessitating insulin therapy.
Who regulates Insulin Delivery Devices in Canada?
Health Canada licenses Class II, III and IV medical devices; Class I devices are sold by companies that hold an establishment licence. Source: Health Canada. Checked 14 Nov 2026.
How is healthcare paid for in Canada?
Each province and territory runs public health insurance under the Canada Health Act, which covers medically necessary hospital and doctor services. Source: Health Canada. Checked 14 Nov 2026.
How many clinical trials on Insulin Delivery Devices are running in Canada?
27 studies are recruiting, active or about to start in Canada, according to ClinicalTrials.gov. Source: ClinicalTrials.gov, Studies recruiting, active or not yet recruiting, in Canada. Retrieved 9 Nov 2026.
What does WHO report for Canada?
Diabetes (adults): 6.8% of adults in 2022, the latest WHO figure. Source: WHO Global Health Observatory, Diabetes (adults, WHO) (% of adults). Retrieved 15 Nov 2026.
How many people in Canada are 65 or older?
20.3% of people were 65 or older in 2025. Source: World Bank Open Data, Population ages 65 and above (% of total population), from UN population estimates. Retrieved 16 Nov 2026.
 Canada


 US
 China
 Japan
 Germany
 France
 UK
 Brazil
 Italy
 Ecuador
 Spain
 India
 Saudi Arabia
 Mexico
 Australia
 South Africa
 UAE
 Egypt
 Philippines
 Hong Kong
 Malaysia
 Singapore
 Thailand
 Kenya
 CeQur
 Amgen Inc.